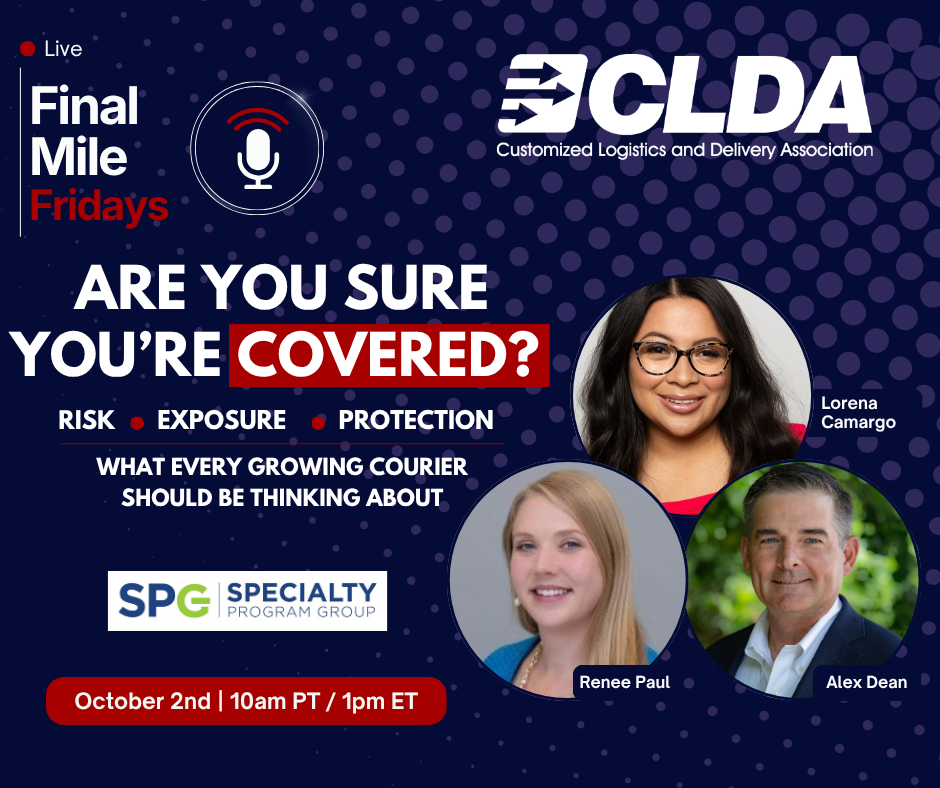
CLDA Final Mile Fridays with Renee Paul and Alex Dean of SPG Transportation
Growth is usually something to celebrate.
More customers. More drivers. More vehicles. New markets. Bigger opportunities.
But growth has a shadow side that final mile operators don’t always see coming.
Every time your business changes, your risk changes with it.
That was the focus of a recent CLDA Final Mile Fridays conversation featuring Renee Paul, SVP of Last Mile Delivery at Specialty Program Group (SPG Transportation), and Alex Dean. The discussion covered how growth creates new insurance exposures — and why operators who don’t think proactively about coverage can find themselves exposed at exactly the wrong moment.
The Risk Shadow: What Growth Leaves Behind
A company can be growing fast and still be dangerously underinsured. Those two things aren’t mutually exclusive.
Think about the operator who started with 20 trucks under one primary contract. That’s a well-defined, manageable risk profile. Now fast-forward: the same company is running 60 trucks, serving multiple 3PL clients, adding white-glove home delivery and using a mix of W-2 drivers and independent contractors. The revenue has tripled — but the insurance program may still look like it did on day one.
That gap is what Renee calls the “risk shadow” — the space between the company you are today and the coverage you put in place when you were something smaller and simpler. The goal isn’t to slow down growth. It’s to make sure your risk management is keeping pace with it.
“Of Course We’re Covered for That”… Maybe Not
One of the most common — and costly — assumptions in this industry is that a coverage limit equals full protection.
Take cargo. An operator looks at the dollar limit on their cargo policy and figures that as long as what they’re hauling is worth less than that number, they’re fine. But commodity type matters. Pharmaceuticals and fine art are examples of cargo that may carry exclusions or require endorsements that a standard policy doesn’t automatically include. Operators moving into new freight categories need to ask the question explicitly — not assume the answer.
Service type matters too. Delivering a package to a doorstep is a different exposure than crossing the threshold into someone’s home to deliver, assemble or install a product. That’s a liability conversation that white-glove operators need to be having with their insurance partners before they sign new contracts — not after a claim surfaces.
Hired and non-owned auto is another area where operators get tripped up. When you’re using independent contractors or vehicles you don’t own, there’s a gap between where the driver’s personal coverage ends and where your company’s exposure begins. Understanding that line — and making sure it’s covered — is critical.
And then there’s contractor compliance — an area Renee is direct about: collecting a certificate of insurance at onboarding is table stakes. The real question is whether that coverage is still in force six months later. Companies that don’t have a process to monitor ongoing compliance are carrying exposure they may not even know about.
Before you take on unfamiliar freight or a new service type, ask: does our current program actually cover what we’re about to do?
Don’t Wait Until Renewal
Growth doesn’t follow your renewal calendar. You might land your largest customer in June, add vehicles in August and launch a new service in October. Renewal isn’t until February. That’s a long time to operate with a program that no longer fits.
Any of the following should trigger a conversation with your insurance partner — before you move forward, not after:
- Adding a significant new customer or contract
- Expanding your fleet — owned or rented vehicles
- Entering a new geographic market
- Introducing a new service type (especially home delivery or installation)
- Changing how you use drivers — W-2 to IC, or vice versa
- Taking on new freight categories
And if you’re negotiating a new contract, send the insurance requirements to your broker before you sign. They can identify gaps, flag requirements that need to be addressed and sometimes help you push back on terms that go further than the exposure warrants.
The goal is to make that call before you’re committed — not after.
Stop Asking How to Lower Your Premium. Start Asking How to Improve Your Risk Profile.
One of the most valuable reframes in the conversation came from Alex: the operators who build the best long-term insurance outcomes aren’t the ones laser-focused on cutting premium. They’re the ones asking a different question.
Instead of: “How do I lower my insurance cost?”
Ask: “How do I improve my risk profile?”
That question opens a very different conversation — one that might include cameras and telematics, MVR monitoring, driver qualification standards, certificate-of-insurance compliance programs and other operational practices that make a company genuinely less risky to insure. Better risk profiles attract better terms. The premium follows.
Your insurance partner should be doing more than processing renewals. They should understand your operation, know where it’s headed and be at the table when you’re evaluating major changes. Think of them the way you’d think of outside legal counsel — someone you bring in before you sign, not after something goes wrong.
Your Risk Shadow Is Growing. Is Your Program?
Winning customers, adding capacity, entering new markets — that’s the work. Nobody should slow that down.
But the company you’re running today may look very different from the one that signed your current insurance program. And that gap — that risk shadow — is where exposure lives.
So ask yourself honestly: does the insurance program you have today actually match the company you’ve become?
If the answer isn’t a confident yes, it’s time to have that conversation.
Watch the Full Conversation
Renee Paul and Alex Dean covered a lot of ground in this Final Mile Fridays episode — hidden cargo exposures, hired and non-owned auto, contractor compliance, risk profiling and more. Watch the full conversation on YouTube and see how these issues might apply to your operation.
Watch the full conversation on YouTube →
Have questions about your program? Connect with Renee, Alex and the SPG Transportation team at spgtransportation.com.
The information shared in this article and the accompanying Final Mile Fridays conversation is intended for general educational purposes and should not be considered legal or insurance advice. Companies should consult with their own insurance, legal and risk-management professionals regarding their specific operations.